info@10xmhub.com
 +971522527368


What Are the UAE Bookkeeping Requirements for Companies?
Published on : September 29, 2026
UAE businesses now face stricter financial rules since recent tax reforms took effect. Bookkeeping has always been a legal obligation in UAE jurisdictions, but the introduction of Corporate Tax has raised the stakes for keeping accurate, up to date records. Companies that overlook this shift risk penalties from tax authorities. Proper financial records give owners a clear read on cash flow while helping them track debts and prepare reports that regulators can trust.
Mainland and Free Zone companies face similar expectations, regardless of sector or annual revenue. Keeping accounts organised not only lowers legal risk but also builds trust with banks and investors. It also gives management a clearer picture of the company’s financial position. Accurate books also ease audits and reduce disputes with tax authorities or partners, giving banks confidence during renewals. Here’s more on bookkeeping requirements in the UAE.
Companies in the UAE need to keep a specific range of financial documents on hand to satisfy audit and reporting rules. General ledgers, bank statements, invoices, receipts, and expense records should account for every transaction the business carries out. Firms registered for VAT carry an added burden: tax invoices, credit notes, and import or export paperwork tied to each taxable supply must be filed.
Corporate tax rules bring their own demands. Companies need records that back up taxable income figures, covering depreciation schedules and dealings between related parties. The Federal Tax Authority (FTA) requires Corporate Tax records to be kept for at least 7 years after the relevant tax period ends, while VAT records usually need to be kept for a minimum of 5 years. Records relating to real estate transactions are subject to a longer retention period, generally 15 years. Free Zone companies answer to the same retention rules, even though they sit under a separate regulatory setup.
Digital record-keeping systems are acceptable, as long as records stay accessible and unaltered when requested by the authorities.
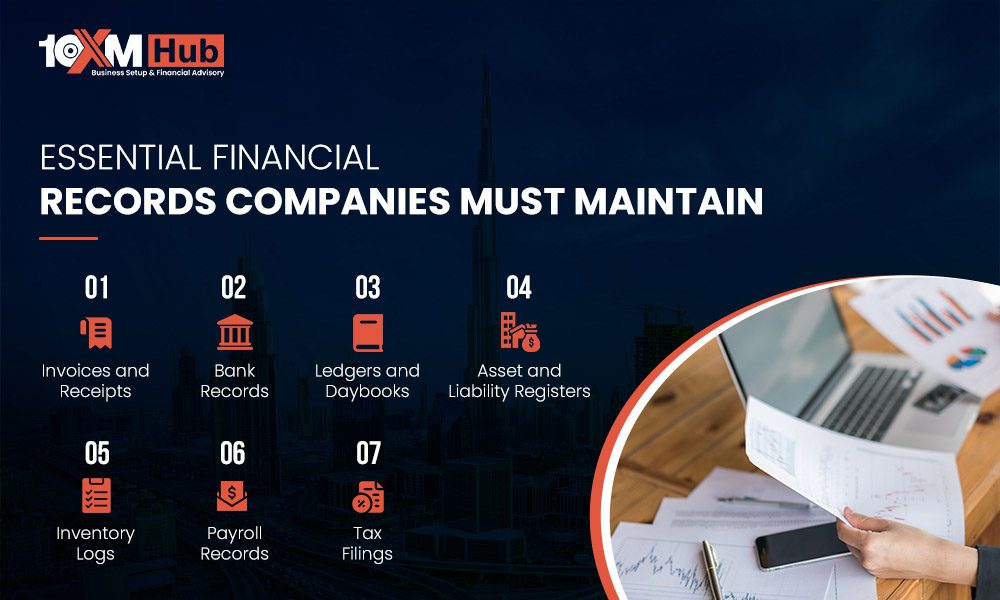
Authorities do not leave this open to interpretation. Every registered entity has to sort its documentation into set categories, and each one gets checked on its own during audits, tax filings, and licence renewals. A single missing category can bring fines from the FTA, regardless of how clean the rest of the business looks.
Also, companies must maintain these documents for specific durations:
| Requirement | Retention Period | Legal Basis |
| Company Accounting Records | Minimum 5 years | UAE Commercial Companies Law |
| VAT Records | Generally minimum 5 years | UAE VAT Law (Federal Decree-Law No. 8 of 2017) |
| Corporate Tax Records | Minimum 7 years | UAE Corporate Tax Law (Federal Decree-Law No. 47 of 2022) |
| VAT Records Relating to Real Estate | Generally 15 years | UAE VAT Law, Real Estate Transaction Directives |
IFRS governs how UAE companies put together their financial statements. That became fixed under Ministerial Decision No. 114 of 2023, tied directly to corporate tax rules, and it covers both Mainland companies and Free Zone entities.
Companies making a revenue not exceeding AED 50 million can opt into IFRS for SMEs, a scaled-back version that trims fair-value calculations and asks for less disclosure.
A few principles hold across both UAE business bookkeeping standards:
Managing accounts in-house pulls time away from higher-value work and leaves staff stretched thin. Bookkeeping services in Dubai bring in specialists who lower operating risk and keep growth on steadier ground.
Keeping compliant financial records is not optional for businesses operating in the Emirates. It’s a legal responsibility that keeps operations in step with Federal commercial law, meets FTA audit standards, and reduces the risks of penalties.
Tracking invoices properly, following IFRS frameworks, and holding onto records for the mandated five-year and seven-year periods gives corporate leaders real control over their commercial assets. These habits also set businesses up for growth that holds steady rather than stalling out during a compliance check.
Handling all of this alone without help for corporate tax bookkeeping UAE takes up significant time which most business owners simply do not have. 10XMHub steps in to reduce that administrative burden, with support for business setup and managing the day-to-day accounting work while keeping filing aligned with local rules.


Share this post :
Turn your network into opportunity. Refer clients to 10XMHub and earn substantial rewards for every successful business setup. We handle your referrals with premium support; you gain trusted commissions and long-term partnership benefits.
Please share your details and we’ll contact you shortly.